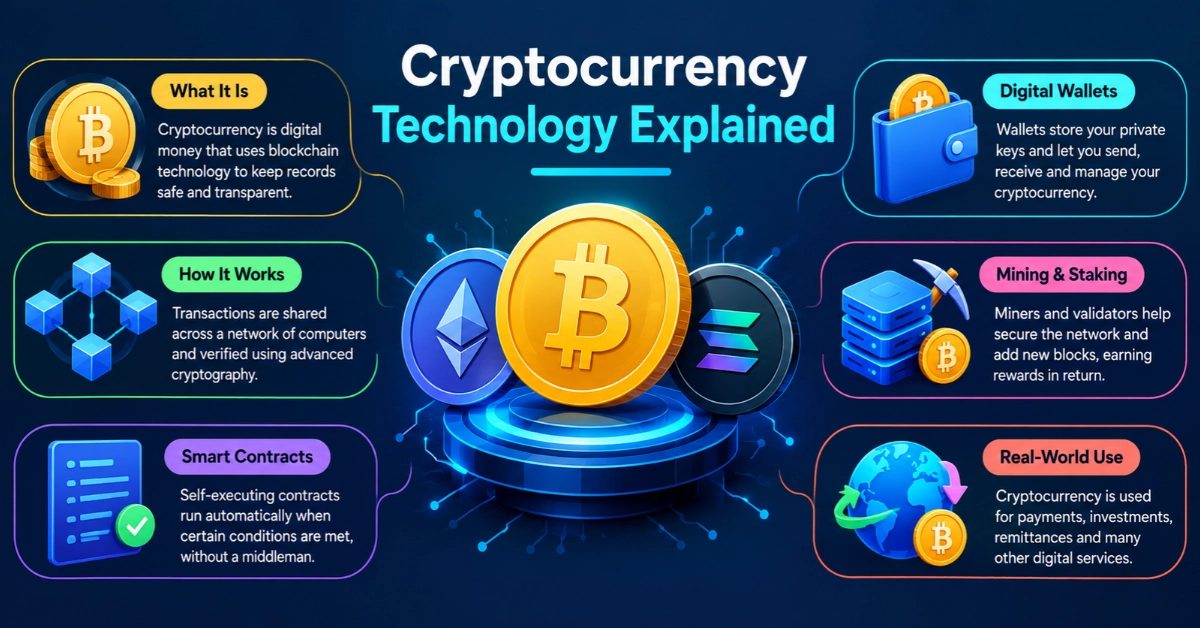
Cryptocurrency technology explained, In simple terms helps people understand how digital money works and how it moves between users. This technology uses blockchain, cryptography and computer networks to record and verify transactions without relying on a central bank. Bitcoin and Ethereum are popular examples of cryptocurrencies that use this technology. It also supports digital wallets, secure payments and smart contracts. Understanding cryptocurrency technology explained step by step makes it easier for beginners to learn how digital currencies work, what benefits they offer and what risks users should know before using them.
Why Was Cryptocurrency Technology Created?
Cryptocurrency technology was created to make digital payments easier, faster and more direct. Traditional payments often depend on banks or other financial institutions to transfer money between people. Cryptocurrency introduced a way for people to send digital money to each other through a computer network without needing a central authority to approve every transaction. It uses blockchain technology to record payments and cryptography to protect transaction details. Bitcoin was created in 2009 as an early example of this idea. Today, cryptocurrency technology is also used for international transfers, digital assets and other online financial services.
How Cryptography Protects Digital Money
Cryptography uses mathematical methods to protect cryptocurrency transactions and digital assets.
- Private Keys: Private keys allow users to control their cryptocurrency and approve transactions.
- Public Keys: Public keys help verify digital signatures without revealing private keys.
- Digital Signatures: They prove that a transaction was approved by someone with the correct private key.
- Cryptographic Hashes: Hashes help detect changes in blockchain records.
- Data Protection: Cryptographic methods help protect transaction information from unauthorized changes.
- Transaction Verification: Network participants use cryptographic proofs to check whether transactions are valid.
Cryptography helps keep digital money secure, but users must also protect their private keys and recovery phrases.
How Cryptocurrency Transactions Work Step by Step
Cryptocurrency transactions follow a series of steps to transfer digital money securely between users.
- Enter Payment Details: The sender enters the receiver’s wallet address and the amount of cryptocurrency to send.
- Sign the Transaction: The sender’s wallet uses a private key to create a digital signature that approves the payment.
- Send to the Network: The signed transaction is shared with computers connected to the cryptocurrency network.
- Verify the Transaction: Network participants check the signature, available funds and transaction rules.
- Add to the Blockchain: A miner or validator helps include the valid transaction in a new block, depending on the network.
- Confirm the Payment: The network records the transaction and the receiver can see the incoming funds in their wallet.
These steps allow cryptocurrency users to transfer digital money without relying on a traditional bank to process every payment.
How Cryptocurrency Networks Agree on Transactions
Cryptocurrency networks use special rules to agree on which transactions are valid. This process is called a consensus mechanism and helps computers maintain a shared blockchain record.
- Proof of Work (PoW): Miners use computing power to solve complex puzzles and help add new blocks to the blockchain.
- Proof of Stake (PoS): Validators lock up cryptocurrency as a stake to help verify transactions and secure the network.
- Transaction Checking: Network participants check whether transactions follow the blockchain’s rules.
- Block Approval: The consensus process helps determine which valid block is added to the blockchain.
- Network Agreement: Participating computers update their records to reflect the accepted transactions.
- Fraud Prevention: Consensus rules make it harder for someone to change records or spend the same coins twice.
Consensus mechanisms help cryptocurrency networks maintain reliable records without relying on one central authority.
How New Cryptocurrency Coins Are Created
New cryptocurrency coins are created through different methods depending on the rules of each blockchain.
- Mining: Some cryptocurrencies, such as Bitcoin, create new coins as rewards for miners who help secure the network.
- Staking Rewards: Some proof-of-stake networks issue new coins to reward validators for helping maintain the blockchain.
- Token Creation: Developers can create digital tokens using smart contracts on existing blockchains.
- Supply Rules: Each cryptocurrency has its own rules for how many coins can be created and distributed.
- Initial Distribution: New coins or tokens may be distributed through sales, rewards or other planned methods.
- Burning Coins: Some projects permanently remove coins from circulation, which can reduce the total supply.
The creation of cryptocurrency depends on its design, network rules and supply plan.
How Smart Contracts Expand Cryptocurrency Technology
Smart contracts expand cryptocurrency technology by running digital agreements automatically when specific conditions are met.
- Automatic Transactions: Smart contracts can transfer digital assets when the required conditions are fulfilled.
- Decentralized Finance: They support services such as lending, borrowing and exchanging digital assets without relying on traditional financial intermediaries.
- Digital Tokens: Developers can use smart contracts to create tokens on supported blockchains.
- Secure Recordkeeping: Contract actions are recorded on the blockchain, making them easier to verify.
- Gaming Applications: Smart contracts can manage in-game assets and digital rewards in blockchain-based games.
- Business Processes: They can automate tasks such as payments and asset transfers according to programmed rules.
Smart contracts make cryptocurrency technology useful for more than digital payments, although coding errors and security risks can still cause losses.
Where Cryptocurrency Technology Is Used in Real Life
Cryptocurrency technology is used in different areas to support digital payments, financial services and online applications.
- Digital Payments: People can use cryptocurrency to pay for certain goods and services where it is accepted.
- International Transfers: Cryptocurrency can help people send digital assets across borders without relying entirely on traditional banking systems.
- Decentralized Finance: Blockchain-based services allow users to access activities such as lending, borrowing and digital asset trading.
- Stablecoins: These digital assets are designed to maintain a stable value by tracking currencies or other reference assets.
- Digital Ownership: Blockchain technology can record ownership of digital items such as artwork, collectibles and in-game assets.
- Business Records: Some businesses use blockchain systems to track products, verify records and improve information sharing.
Cryptocurrency technology supports many digital activities, but its usefulness depends on security, costs, local laws and real-world acceptance.
Benefits, Risks and the Future of Cryptocurrency Technology
Cryptocurrency technology offers useful opportunities, but it also has risks and challenges that users should know.
- Direct Payments: Cryptocurrency allows people to send digital assets to others without needing a bank to process every transaction.
- Transparent Records: Public blockchains allow people to check recorded transactions and verify information.
- Security Risks: Stolen private keys, scams and software weaknesses can lead to permanent financial losses.
- Price Changes: Many cryptocurrencies have highly changing prices, which can make their value difficult to predict.
- Energy and Scaling Challenges: Some networks use large amounts of energy while others face limits on transaction speed and capacity.
- Future Developments: Better scaling systems, improved security tools and wider blockchain applications may make the technology more useful in the future.
Cryptocurrency technology may continue to develop, but its long-term success will depend on security, practical use, responsible development and clear regulations.
Common FAQs About Cryptocurrency Technology Explained
Here are some FAQs of Cryptocurrency Technology Explained:
Can Cryptocurrency Technology Work Without the Internet?
Most public cryptocurrency networks require an internet connection to broadcast and verify transactions, although some offline methods can help prepare transactions.
Can a Cryptocurrency Transaction Be Reversed?
Most confirmed blockchain transactions cannot be reversed easily. If a payment is sent to the wrong address, recovering the funds may be difficult or impossible.
What Is a Cryptocurrency Node?
A node is a computer that connects to a cryptocurrency network and helps share or check transaction and blockchain information.
Can Two Cryptocurrencies Use the Same Blockchain?
Yes, multiple cryptocurrencies and tokens can operate on the same blockchain if its technology supports them.
What Is a Layer 2 Cryptocurrency Network?
A Layer 2 network works alongside a main blockchain to help process transactions more efficiently and reduce congestion or fees.
Does Every Cryptocurrency Have a Limited Supply?
No, some cryptocurrencies have a fixed maximum supply while others can create additional coins according to their network rules.
What Happens If a Cryptocurrency Project Stops Operating?
The blockchain may continue running if enough independent participants maintain it, but its value, development and user activity could decline.
Can Cryptocurrency Technology Be Used Outside Finance?
Yes, blockchain-based systems can support digital identity, supply-chain tracking, digital ownership records and other applications beyond payments.
Final Conclusion
Cryptocurrency technology has changed how people think about digital money and online transactions. It combines blockchain, cryptography and digital networks to support secure recordkeeping and direct transfers. This technology also supports smart contracts, digital assets and various online services. However, challenges such as security risks, price changes and network limitations remain important. As technology develops, cryptocurrency may offer new opportunities for individuals and businesses. Understanding how it works, along with its benefits and risks, can help people make informed decisions about its use.